Digital Door Lock System Market Surge Driven by Smart Home Adoption & Matter Protocol
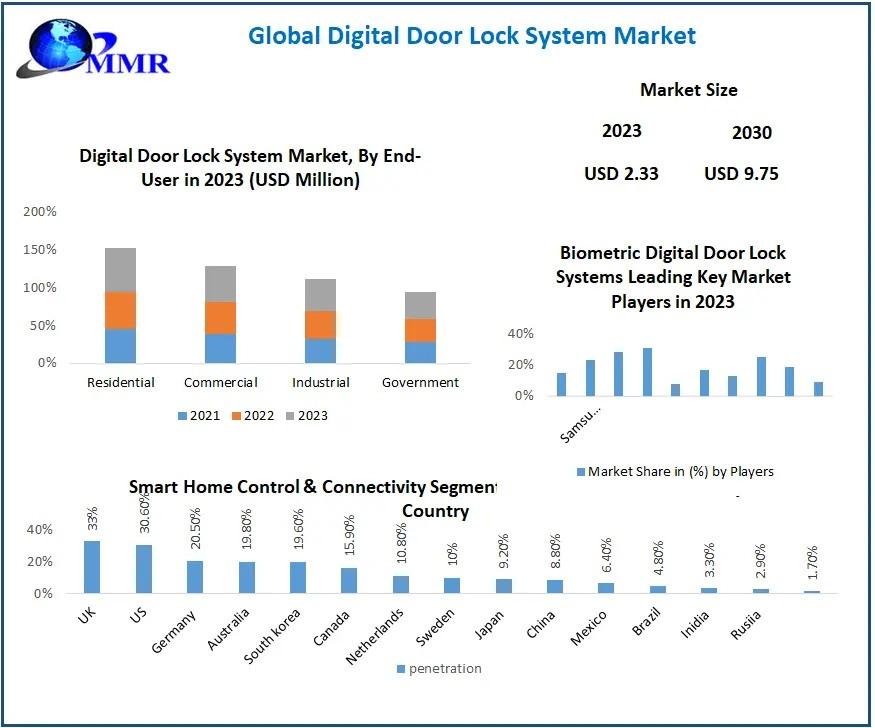
Global Digital Door Lock System Market Accelerates from USD 3.11 Billion in 2025 toward USD 11.37 Billion by 2034, Registering a 15.5% CAGR as Keyless Access Networks, Next-Generation Biometrics, and Integrated Smart Infrastructure Transform Modern Security Architecture
Executive Market Intelligence on Deadbolts, Smart Mortise Locks, Ultra-Low-Power Edge Biometrics, Touchless Mobile Credentials, Multi-Tenant Cloud Provisioning, Hospitality Automation, and Global Real Estate Retrofits
The global residential construction industry, enterprise facility operations, commercial real estate portfolios, and high-end hospitality sectors are navigating a decisive architectural pivot away from mechanical key security toward digital, interconnected access control networks. For over a century, structural security depended almost exclusively on pin-and-tumbler deadbolts, physical brass keys, and mechanical master-key systems. While mechanical cylinders provided basic physical locking, they inherently exposed properties to unauthorized key duplication, lock manipulation, non-existent entry logging, and substantial operational costs each time a cylinder required physical replacement. In today’s interconnected environment, defined by rising urban population density, the expansion of multifamily rental properties, growing smart home ecosystems, and mobile credential usage, physical security operations demand higher administrative agility, traceable user access, and seamless remote management. Consequently, global access management is rapidly transitioning to intelligent, electromechanical digital door lock architectures. Maximize Market Research, an international market intelligence and corporate strategy advisory firm, has unveiled its thorough strategic report titled "Global Digital Door Lock System Market: Architecture Typology, Authentication Methodology, Protocol Dynamics, End-Use Real Estate Segments, Competitive Strategy Benchmarking, and Long-Term Market Forecast (2026-2034)."
The market intelligence publication provides an in-depth examination of biometric fingerprint recognition, structured-light 3D facial authentication, digital capacitive touchpads, RFID proximity smart cards, Bluetooth Low Energy (BLE), Wi-Fi-enabled deadbolts, cloud-based property management software, and emerging Matter-over-Thread mesh access protocols. Valued at USD 3.11 Billion in 2025 and projected to reach USD 11.37 Billion by 2034, expanding at an aggressive Compound Annual Growth Rate (CAGR) of 15.5%, the global digital door lock system industry is absorbing sustained commercial and residential capital investments. This structural expansion is underpinned by the widespread adoption of consumer IoT platforms, consumer migration toward keyless daily living, large-scale multi-unit housing renovation programs, and advancements in energy-efficient microcontrollers that deliver dependable multi-year battery operation.
𝐃𝐨𝐰𝐧𝐥𝐨𝐚𝐝 𝐏𝐃𝐅 𝐁𝐫𝐨𝐜𝐡𝐮𝐫𝐞 @ https://www.maximizemarketresearch.com/request-sample/15375/
For full access to the comprehensive strategic report, visit: https://www.maximizemarketresearch.com/market-report/global-digital-door-lock-system-market/15375/
Executive Summary and Structural Industry Drivers
A digital door lock system represents an electromechanical locking unit designed to actuate internal motorized deadbolts, heavy-duty latches, or solenoids through digital credentials rather than mechanical keys. Controlled via numerical PIN credentials, optical or capacitive biometric fingerprint impressions, 3D facial mapping scans, high-frequency RFID cards, or encrypted mobile digital keys transmitted via BLE or NFC, modern digital systems deliver robust mechanical integrity combined with actionable digital access oversight. Advanced connected lock architectures enable dynamic credential provisioning: residential owners and corporate property directors can instantly generate time-restricted access passes, observe real-time audit trails detailing entry timestamps, and manage exterior door locks remotely through enterprise cloud management applications.
The rapid worldwide expansion of the digital door lock ecosystem is driven by several operational, social, and technological market forces:
-
Expanding Global Smart Home Penetration and Voice Automation: Modern residential living has moved beyond isolated smart gadgets into fully orchestrated smart home environments, with tens of millions of residences actively running central automation networks. Digital door locks serve as a cornerstone of residential entrance automation. Through integration with widespread home automation ecosystems, including Apple Home, Amazon Alexa, Google Home, and Samsung SmartThings, digital locks trigger coordinated automated actions, such as locking exterior perimeters upon arming home alarms, activating entry lighting upon authorized fingerprint scans, and providing hands-free voice-controlled operation.
-
Rapid Expansion Across Multifamily Real Estate and Short-Term Hospitality Rentals: Operational management for multi-tenant apartment developments, modern student housing, and short-term vacation rental portfolios has generated significant demand for digital lock upgrades. The ongoing expense of manual lock re-keying and physical key handovers during tenant turnover generates substantial operational overhead for property managers. Digital door locks eliminate physical key turnover entirely. Property teams can remotely generate time-restricted passcodes, grant secure digital keys, or cancel credentials directly from a centralized cloud console, lowering property maintenance expenditures and eliminating the security liabilities of unreturned physical keys.
-
Widespread Consumer Adoption of High-Speed Biometric Authentication: Daily consumer interaction with fingerprint sensors and facial authentication on modern mobile devices has made biometric identity verification standard. Lock manufacturers are responding by embedding advanced capacitive and 3D optical fingerprint scanners directly into door pull handles and outer lock casings, enabling natural single-motion access in under half a second. Additionally, advancements in energy-efficient structured-light 3D infrared facial recognition enable touchless verification even in total darkness, utilizing on-device edge neural processors to prevent spoofing from printed photographs or digital video displays.
-
Unified Connectivity Standards via Matter and Thread Protocols: Fragmentation across proprietary communication protocols has historically complicated smart lock deployment, forcing consumers and integrators to choose between specialized Z-Wave, Zigbee, or power-intensive standalone Wi-Fi hubs. The rollout of Matter operating across low-power Thread mesh networks has transformed IoT hardware compatibility. Matter-certified digital locks connect directly to existing smart home hubs without secondary manufacturer bridges, drastically reducing latency, extending operational battery life to over a year, and facilitating interoperability across competing smart home hardware brands.
Emerging Industry Obstacles and Strategic Complications
Even as overall adoption accelerates across major global housing and commercial markets, hardware developers, security architects, property owners, and software engineers must address complex technological, operational, and regulatory challenges:
1. Hardware Cybersecurity, Device Vulnerabilities, and Network Exploit Defense
Because digital locks control physical entry to family residences, enterprise facilities, and sensitive corporate suites, they represent attractive targets for digital intrusion. Software vulnerabilities in unencrypted communication handshakes, insecure application programming interfaces (APIs), or unpatched firmware can expose systems to replay attacks or unauthorized remote activation. With escalating consumer and corporate losses attributed to global cybercrime, regulatory bodies are actively imposing stringent IoT device security benchmarks, including the U.S. Cyber Trust Mark and the European Cyber Resilience Act. Hardware developers must incorporate dedicated secure element (SE) chips, high-grade AES-128/256 encryption, and tamper-proof over-the-air (OTA) firmware architectures to protect physical safety and comply with emerging cybersecurity laws.
2. Environmental Degradation, Physical Weathering, and Battery Depletion Concerns
Unlike interior consumer electronics that operate within stable ambient temperatures, exterior entrance locks must withstand extreme environmental conditions. Exterior escutcheons are routinely subjected to direct solar exposure, extreme freeze-thaw temperature swings ranging from -30°C to +70°C, high humidity, and corrosive coastal salt air, demanding ruggedized IP65 or higher ingress ratings. Concurrently, consumers experience power anxiety regarding the potential of being locked out if internal AA alkaline or rechargeable lithium-ion cells run out of power. Manufacturers must design systems with hidden physical key overrides, clear low-voltage warnings, and exterior emergency USB-C jump ports to preserve reliable access during power failures.
3. High Upfront Hardware Costs and Varied Architectural Door Dimensions
The upfront purchase price of a high-tier biometric or wireless digital door lock—typically between USD 150 and USD 600—remains noticeably higher than standard mechanical locksets. Furthermore, global architectural door construction varies significantly by region: North American residential buildings predominantly utilize tubular cylindrical deadbolts with standard backset dimensions; European architecture is built around DIN-standard profile cylinders and complex multi-point mortise systems; while Asian urban developments favor massive mortise lock configurations with integrated push-pull handles. Engineering modular, retrofittable lock assemblies that integrate cleanly across diverse regional door preparations without requiring professional door modifications remains a key operational challenge.
In-Depth Segmental Assessment: Typology, Biometrics, Connectivity, and End-User Demands
The strategic industry report evaluates the global digital door lock system landscape across core mechanical designs, technological capabilities, and end-user real estate segments:
Product and Mechanical Typology: Deadbolts, Mortise Assemblies, and Smart Lever Locks
-
Deadbolt Locks: The largest product segment in North American single-family residential retrofits. Electronic deadbolts replace or reinforce standard manual deadbolts, utilizing motorized bolt extensions to offer dependable resistance against physical force attacks while enabling simple DIY installation.
-
Mortise Locks: The standard high-security lock configuration across European residential structures, Asian urban apartment buildings, corporate office facilities, and high-end hotels. Mortise assemblies integrate heavy-duty latchbolts and hardened deadbolts within a single recessed chassis inside the door core, delivering exceptional mechanical resistance and seamless handle-pull operation.
-
Lever and Knob Locksets: Widely specified for interior residential suites, executive offices, rental bedrooms, and sensitive storage rooms where full exterior deadbolt resistance is unnecessary, integrating digital keypads or biometric sensors into the operational handle.
-
Rim Locks and Specialized Smart Padlocks: Serves unique installation environments, including interior glass partitions, surface-mounted apartment doors where drilling is prohibited by lease agreements, and industrial utility enclosures.
Authentication Technology Dynamics: Advanced Biometrics alongside Resilient Keypads
-
Biometric Authentication (Fingerprint, Facial Recognition, and Iris Scanning): The fastest-growing authentication category by market valuation. Biometric solutions remove the need to manage physical cards or remember complex PIN codes. Capacitive fingerprint sensors built into pull handles dominate retail volume, while advanced 3D structured-light facial scanners represent the premium luxury residential and high-security enterprise segment.
-
Electronic Touchscreen Keypads (PIN Code Entry): The primary and most reliable electronic entry method globally. Keypads remain essential across multifamily developments and vacation rentals due to low production costs, extreme mechanical durability, and the simplicity of creating temporary, dynamic visitor passcodes.
-
RFID and Smart Cards (NFC and Proximity Cards): The primary entry method across corporate enterprise campuses, educational facilities, and global hotel properties. Low-cost RFID cards and keyfobs allow property managers to manage, issue, and revoke access privileges across high-turnover user bases.
-
Mobile Access Credentials (BLE and NFC Smartphone Unlocking): Experiencing rapid double-digit growth across commercial workplaces and modern residential properties. Utilizing Bluetooth Low Energy or Near Field Communication, users open access points by tapping their mobile phone, wearing an authorized smartwatch, or walking toward the door using hands-free proximity recognition.
Communication Protocols: Expansion of Matter and Thread Alongside Direct Wi-Fi
-
Wi-Fi Connectivity: Delivers direct, bridge-free remote connectivity to cloud platforms and home internet routers. While Wi-Fi smart locks offer user-friendly setup and instant remote alerts from anywhere, higher battery consumption requires frequent cell replacement or dedicated rechargeable lithium battery packs.
-
Bluetooth Low Energy (BLE): Provides energy efficiency, enabling multi-year runtimes on standard alkaline batteries. BLE serves as the primary protocol for close-range mobile device pairing and direct access provisioning.
-
Matter and Thread Mesh Networks: The unifying standard across the smart home sector. Operating over low-latency, self-healing IPv6 wireless mesh networks, Thread enables digital locks to communicate directly with smart home hubs while lowering energy consumption compared to conventional Wi-Fi.
-
Z-Wave and Zigbee Networks: Established protocols in professional smart home installations and monitored residential security packages, valued for reliable signal coverage and low operational power requirements.
Real Estate Applications: Single-Family Homes, Multifamily Housing, and Commercial Offices
-
Residential Real Estate (Single-Family, Multifamily, and Luxury Condominiums): Captures the largest and fastest-growing revenue share globally. Driven by consumer desires for smart convenience, secure package delivery, and safe family access, digital locks have evolved from early-adopter luxuries into standard home amenities.
-
Hospitality and Hotel Properties: A crucial commercial volume driver. International hotel conglomerates are upgrading properties to offer contactless mobile check-in. Guests bypass front-desk queues, receiving encrypted room keys directly in their smartphone digital wallets to unlock their rooms upon arrival.
-
Commercial Corporate Offices and Flexible Workspaces: Driven by demand for centralized access controls, visitor management platforms, and automated room reservations that integrate directly with enterprise corporate software.
-
Government Facilities, Healthcare Complexes, and Educational Campuses: Demands high-grade biometric access systems, tamper logging, and centralized lockdown functions to secure pharmaceutical stores, research laboratories, and institutional offices.
Comprehensive Regional Industry Analysis
The worldwide geographic footprint highlights varied regional technology adoption rates, door engineering conventions, and connected living environments:
North America
Holding the leading position in total market revenue in 2025, North America serves as the primary innovation and consumer deployment center for digital door lock systems. The United States drives regional growth, powered by high disposable incomes, high smart home adoption, and a massive housing inventory based on standardized tubular deadbolts ideal for direct consumer retrofits. Additionally, major domestic hardware manufacturers have integrated smart locks with home automation platforms, vacation property portals, and monitored security systems. Rapid adoption across large-scale multifamily rental developments across the southern and western United States continues to drive steady commercial demand.
Asia-Pacific
Projected to deliver the fastest compound annual growth rate through 2034, the Asia-Pacific region represents the highest-volume manufacturing and consumer market. Driven by dense urban populations living in modern condominium developments, extensive smart city projects, and high cultural acceptance of keyless access, adoption is widespread across South Korea, China, Japan, India, and Southeast Asia. South Korea has the world's highest digital lock adoption rate, where electronic mortise systems have been standard in urban apartments for decades. China serves as the dominant manufacturing and volume market, supported by strong domestic demand for facial recognition and push-pull smart handles. In India, rapid urban growth, rising household incomes, and premium residential construction across metropolitan regions are fueling a large-scale shift toward biometric handles and smart deadbolts.
Europe
The European landscape is characterized by rigorous physical security benchmarks (such as EN 1303 mechanical standards), diverse historical architecture, and strict personal data privacy laws under GDPR. Led by Germany, the United Kingdom, France, Italy, and the Nordic countries, European property owners prioritize high-grade mechanical resilience, understated architectural designs, and secure local data handling. Unlike North America's deadbolt-centric market, European construction relies heavily on DIN-standard Euro-profile cylinders and multi-point mortise locksets. In response, European manufacturers lead in developing motorized smart cylinders and retrofittable indoor lock adapters that sit over existing keys on the inside of the door, preserving exterior aesthetics and traditional mechanical key capability.
Middle East and Africa
Supported by substantial high-end commercial property developments, luxury residential smart communities, and major hospitality investments in the United Arab Emirates and Saudi Arabia, the Middle East is an attractive, high-margin market for premium biometric access hardware. Modern real estate projects in Dubai and Riyadh routinely integrate 3D facial recognition locks and automated home control platforms into new properties. In Africa, demand is concentrated across corporate headquarters, banking centers, and gated communities in South Africa, Kenya, and Nigeria, where property owners rely on biometric systems for asset protection.
Latin America
The Latin American market, anchored by Brazil, Mexico, and Colombia, is recording steady industrial and residential expansion. Expanding urban middle-class populations and growing personal security awareness are driving adoption of keypad deadbolts and biometric entry systems. In Mexico, proximity to the United States supports contract manufacturing of electronic lock components, while luxury hospitality properties across regional tourist corridors are adopting contactless mobile locks to streamline guest experiences.
Strategic Vision: Moving from Isolated Hardware to Ambient, Autonomous Access
The digital door lock is evolving from a standalone battery-operated physical lock into an intelligent, ambient access point within integrated spatial computing ecosystems. Over the next decade, market leadership will be determined by four foundational technological vectors:
-
Ultra-Wideband (UWB) Hands-Free Spatial Awareness: While standard Bluetooth requires users to tap their phones or wait briefly for a wireless handshake, Ultra-Wideband (UWB) microchips provide precise positioning down to the centimeter. Locks equipped with UWB calculate the exact distance, speed, and approach angle of an authorized user carrying an active smartphone or smartwatch. The door unlocks automatically as the user reaches for the handle, remaining safely locked if they simply walk past the entrance on the inside of the home.
-
Energy-Harvesting Self-Powered Lock Engineering: Ongoing battery changes present an operational pain point for smart locks. Next-generation residential and commercial locks will incorporate ambient-light solar cells on exterior escutcheons and micro-kinetic generators inside mechanical handle levers. Turning the door handle or closing the latch converts mechanical energy into electricity, charging internal solid-state batteries and enabling decades of maintenance-free operation without battery swaps.
-
Unified Video Intercom and Smart Lock Form Factors: Consumers previously had to purchase and install two distinct devices: an electronic deadbolt and an external video doorbell. The industry is rapidly merging these products into unified video smart locks. A single door assembly now houses a high-definition 2K HDR camera, two-way audio communications, 3D facial recognition sensors, and a motorized deadbolt, providing front-door video surveillance, visitor interaction, and electronic access in a single installation.
-
Zero-Knowledge Decentralized Access Credentials: As smart properties adopt decentralized digital identity frameworks, physical door access will utilize zero-knowledge cryptographic authentication and blockchain-verified keys. Rather than transmitting biometric templates or private personal data to centralized cloud servers, identity checks are executed locally on the user's mobile device, proving entry authorization to the lock without exposing private biometric information.
Strategic Directives for Hardware OEMs, Integrators, and Real Estate Developers
To expand market share, protect operating margins, and lead the technical evolution of physical security access, corporate leadership and engineering teams must execute targeted operational strategies:
-
Adopt Matter-over-Thread Connectivity Across All Product Roadmaps: Equipment manufacturers must make Matter-over-Thread certification a standard requirement across new lock designs. Removing external Wi-Fi bridges and ensuring seamless operation with Apple Home, Google Home, and Amazon Alexa simplifies consumer setup, minimizes battery drain, and secures prime retail and commercial distribution.
-
Incorporate Hardware-Level Secure Element Cryptographic Protection: Given rising consumer and regulatory concerns regarding IoT vulnerabilities, lock manufacturers must integrate dedicated secure element (SE) chips and FIPS-compliant cryptographic modules into device circuit boards. Deploying encrypted wireless links and secure firmware updates protects users against digital intrusion and establishes long-term consumer brand trust.
-
Develop Flexible Modular Retrofit Platforms for Global Markets: To scale globally without maintaining dozens of fragmented regional product architectures, manufacturers should design modular lock mechanisms. Creating a universal electronic and biometric processing core that works with interchangeable regional chassis—including North American cylindrical deadbolts, European profile cylinders, and Asian mortise locks—lowers development expenses and accelerates global rollouts.
-
Partner with Property Management Platforms to Generate Recurring SaaS Revenue: The multi-tenant residential and commercial sectors offer substantial software revenue opportunities. Hardware makers should move beyond one-off hardware sales by delivering complete access-management-as-a-service (SaaS) platforms. Providing commercial property owners with subscription-based tools for remote credential management, automated lease turnover, and contractor access establishes predictable, high-margin recurring income.
Competitive Dynamics and Major Industry Stakeholders
The global digital door lock system industry features a competitive mix of international hardware conglomerates, specialized biometric developers, smart home innovators, and consumer electronics brands.
Prominent market participants evaluated in the report include:
-
ASSA ABLOY Group (Yale / August Home)
-
Allegion plc (Schlage)
-
Spectrum Brands Holdings, Inc. (Kwikset / Baldwin)
-
Dormakaba Holding AG
-
Salto Systems S.L.
-
Samsung SDS Co., Ltd. / Zigbang Co., Ltd.
-
Kaadas Group
-
Xiaomi Corporation
-
Desi Alarm and Security Systems Inc.
-
Panasonic Holdings Corporation
-
Godrej & Boyce Manufacturing Company Limited
-
Master Lock Company LLC (Fortune Brands Innovations)
-
Level Home Inc.
-
Lockly (PIN Genie, Inc.)
-
Latch Systems, Inc.
Industry participants are actively competing by introducing unified video door locks, expanding 3D facial authentication lines, earning Matter-over-Thread certifications, and securing access control supply contracts with global hotel brands and commercial multi-unit residential developers.
Research Methodology and Analytical Principles
The findings, projections, and market sizing models in Maximize Market Research’s report are developed through a multi-tiered analytical research methodology. Primary research incorporates detailed technical interviews, industry briefings, and structured surveys with chief technology officers at door hardware companies, smart home system architects, commercial property managers, hospitality security leads, and IoT cybersecurity researchers across North America, Asia-Pacific, Europe, the Middle East, and Latin America.
Secondary research involves exhaustive review of international hardware safety standards (including ANSI/BHMA certifications, UL 10C fire tests, and European EN standards), smart home industry alliance documentation, annual corporate filings (Form 10-K), global shipping records, and patent databases covering low-power wireless protocols and biometric algorithms. All data inputs are triangulated using bottom-up housing construction tracking, lock replacement rate models, Porter’s Five Forces competitive analysis, and macroeconomic PESTEL assessments to deliver dependable, investment-grade market intelligence.
Official Report Access Links
To download sample data sheets, review comprehensive segment analyses, or arrange customized research consulting, access the official report links:
-
𝐃𝐨𝐰𝐧𝐥𝐨𝐚𝐝 𝐏𝐃𝐅 𝐁𝐫𝐨𝐜𝐡𝐮𝐫𝐞 @ https://www.maximizemarketresearch.com/request-sample/15375/
-
For full access to the comprehensive strategic report, visit: https://www.maximizemarketresearch.com/market-report/global-digital-door-lock-system-market/15375/
About Maximize Market Research
Maximize Market Research publishes sector forecasts, competitive analysis, and consulting insight for teams evaluating demand, competition, pricing, and growth strategy across high-value industries. The firm supports multinational security conglomerates, electronic lock manufacturers, smart home device makers, real estate developers, and private equity technology funds worldwide with empirical research methodologies and strategic business consulting.
Global Corporate Headquarters and Direct Inquiries
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: [email protected]
Website: www.maximizemarketresearch.com
- Digital Agency
- Literie
- Location de voitures
- Restaurant
- Restaurant
- Mode
- Mode
- Information
- Marketing
- Tourisme
- Développement
- Découverte
- Législation
- Gastronomie
- Pâtisserie
- مناسبة
- Art
- Causes
- Crafts
- Dance
- Drinks
- Film
- Fitness
- Food
- الألعاب
- Gardening
- Health
- الرئيسية
- Literature
- Music
- Networking
- أخرى
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
 Arabic
 Indian
 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek