The Ultimate Real Estate Crossroads: Weighing Custom Construction Against Existing Property Acquisition
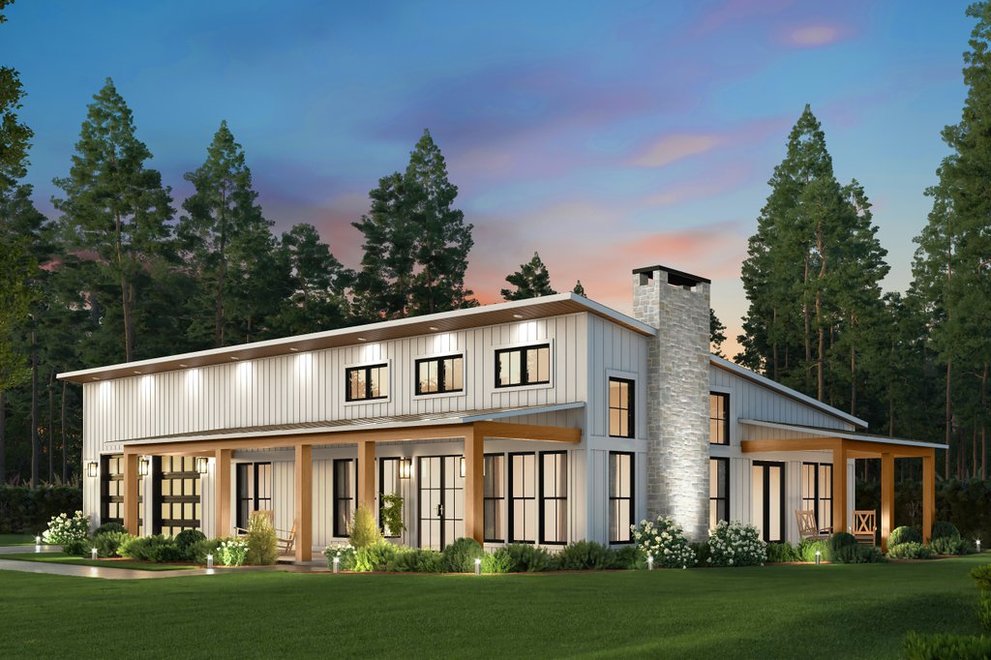
Stepping into the housing market is one of the most monumental financial and personal milestones you will ever undertake. Whether you are a first-time buyer looking to establish roots or an experienced homeowner preparing for your next chapter, the decision between constructing a brand-new residence and purchasing an existing structure shapes your lifestyle and financial portfolio for decades. The modern real estate landscape offers distinct paths, and evaluating whether to build vs buy a home requires a rigorous, multi-faceted analysis. While buying an established house provides immediate shelter, predictable closing timelines, and mature neighborhood environments, building a bespoke property gives you complete creative freedom over architectural layouts, energy efficiency standards, and custom interior finishes. However, diving into custom construction requires navigating a specialized financial ecosystem completely distinct from traditional retail mortgages. Understanding how these financial mechanics, zoning laws, site preparation demands, and long-term maintenance obligations interact is essential for making an informed investment that aligns seamlessly with your overarching personal goals.
The Core Philosophy of Real Estate: Custom Design Versus Established Living
At the heart of the homeownership debate lies a fundamental conflict between absolute personalization and immediate convenience. When you purchase an existing property, you are buying a finalized product within a fixed historical context. The floor plan, structural orientation, and neighborhood demographics are already set in stone. You can certainly execute cosmetic renovations—such as repainting walls, replacing kitchen countertops, or laying down new flooring—but you are ultimately working around someone else's architectural choices.
Conversely, embarking on a custom construction journey turns you into the visionary director of your living environment. Every structural angle, ceiling height, window placement, and mechanical system is engineered around your exact daily routines and aesthetic preferences. This level of customization ensures that your home adapts to your family's needs rather than forcing your family to adapt to an inflexible space. However, this creative freedom demands immense patience, active decision-making, and a high tolerance for project management.
Financial Architecture: Understanding Upfront Capital and Cash Flow
The financial mechanisms governing custom construction are vastly different from those of standard real estate purchases. When buying an existing house, lenders evaluate an established, physical asset and issue a lump-sum mortgage at closing. The underwriting process is relatively straightforward, and you can typically move in within 30 to 60 days of your offer being accepted.
Building a custom home, on the other hand, requires a short-term financing vehicle tailored specifically to the phases of construction. Because the bank is lending money against a property that does not yet exist, risk management is significantly more stringent. This is where specialized construction loans for custom homes become indispensable. Unlike traditional mortgages, these loans disburse capital incrementally through scheduled milestone draws, ensuring funds are released only after independent inspectors verify physical progress on the job site. Borrowers typically make interest-only payments during the active building phase based strictly on the capital drawn, keeping monthly overhead manageable until the project receives its final certificate of occupancy and converts into a permanent mortgage.
Comparative Metrics: Building Custom Versus Purchasing Existing
To clearly evaluate how these two real estate strategies diverge across operational, financial, and logistical dimensions, reviewing a structured comparison can provide valuable perspective.
| Evaluation Metric | Custom Home Construction | Purchasing an Existing Property |
| Average Timeline | 8 to 24 months (includes land purchase, design, and permits) | 30 to 60 days (from purchase contract to closing) |
| Financing Structure | Short-term construction loan transitioning to permanent mortgage | Traditional fixed or adjustable-rate mortgage |
| Initial Down Payment | Typically 10% to 20%+ of total project cost | 3% to 20% down payment based on loan program |
| Design Control | 100% control over layout, materials, and smart home tech | Restricted to cosmetic updates and layout renovations |
| Initial Maintenance | Minimal; brand-new systems, modern insulation, and warranties | Variable; older roofs, plumbing, or HVAC may need repair |
| Location & Setting | Freedom to select raw acreage or suburban lots | Restricted to active housing inventory in mature areas |
The Hidden Realities of Land Acquisition and Site Preparation
One of the most significant variables that catches prospective custom builders off guard is the financial and administrative weight of land development. When you buy an existing home, the land, grading, driveway, and utility hookups are already fully integrated into the purchase price. When you build custom, securing the raw land is merely the first step.
Geotechnical Challenges and Foundation Engineering
Before a single architectural blueprint can be approved, a comprehensive geotechnical soil report is mandatory. The composition of the earth beneath your proposed building footprint dictates your structural engineering expenses. If soil testing reveals expansive clay, soft loam, or unyielding subterranean rock, you may face expensive remediation requirements. These can include deep concrete pier foundations, soil stabilization additives, or heavy rock-blasting machinery. Furthermore, building on a sloped lot requires extensive excavation, terracing, and heavy-duty retaining walls to prevent long-term erosion.
Bringing Utilities to Raw Land
Hooking up to municipal water, sewer, electrical, and natural gas lines in a developed suburban subdivision is relatively straightforward, though connection tap fees still apply. However, if your property is located in a rural or acreage setting, bringing modern infrastructure to the site can become a major capital expenditure. Drilling a private water well, installing an engineered septic tank system, and running hundreds of feet of electrical conduit from the main public road involve significant upfront costs that standard builder base contracts routinely exclude.
Navigating Municipal Permitting and Administrative Compliance
The modern construction industry is heavily regulated by local, county, and state governments to ensure that all new residential structures meet strict structural safety, health, and environmental codes. Navigating this bureaucratic landscape is a mandatory phase of the building lifecycle.
Municipal building departments charge substantial fees to review architectural plans, issue structural permits, and conduct progressive inspections at key milestones such as foundation pouring, framing, and rough-in plumbing. In addition to standard building permits, many growing municipalities levy development impact fees. These charges help fund the expansion of local public infrastructure, including public schools, emergency services, and road networks, to support new residential growth. Failing to budget for these non-negotiable administrative fees can quickly strain your contingency reserves.
Maintenance Projections and Long-Term Operating Costs
When evaluating the long-term economics of homeownership, ongoing maintenance and energy efficiency play a massive role in your household budget.
The Efficiency of Modern Construction
A newly constructed custom home is built to the latest energy efficiency standards. High-performance double or triple-pane windows, advanced spray foam insulation, modern HVAC zoning, and LED architectural lighting drastically reduce monthly utility consumption. Furthermore, major structural components—such as the roof, plumbing network, electrical panel, and kitchen appliances—come with manufacturer warranties, guaranteeing zero major repair overhead during the first decade of occupancy.
The Hidden Liabilities of Older Homes
While older homes in established neighborhoods offer undeniable charm, mature trees, and convenient proximity to urban centers, they frequently harbor hidden liabilities. An aging roof nearing the end of its lifespan, cast-iron plumbing pipes prone to corrosion, or an outdated electrical panel incapable of handling modern high-voltage demands can lead to catastrophic repair bills shortly after closing. Renovating an older home to match contemporary energy efficiency and open-concept standards can easily equal or exceed the cost of building new.
Conclusion
Choosing how to achieve your ideal living situation requires an honest assessment of your financial liquidity, timeline flexibility, and personal appetite for project management. Constructing a bespoke residence gives you complete creative autonomy, ensuring that every square inch of your environment caters precisely to your lifestyle while offering top-tier energy efficiency. Conversely, purchasing an established property provides immediate shelter, predictable closing timelines, and the comfort of a mature neighborhood, albeit with inherited layout constraints and potential maintenance liabilities. By carefully weighing these factors against your long-term wealth strategy, you can confidently navigate the real estate market and secure a property that serves as both a functional personal sanctuary and a robust economic investment.
Frequently Asked Questions
What are the main financial differences between a construction loan and a traditional mortgage?
Construction loans are short-term credit vehicles designed to disburse funds in phased milestone draws as building progresses, typically requiring interest-only payments during the build phase. Traditional mortgages fund the entire purchase price of an existing property in a single lump sum at closing, immediately initiating principal and interest payments.
Why do custom building timelines often exceed initial expectations?
Pre-construction phases—including architectural design, engineering reviews, geotechnical soil testing, and local municipal permit approvals—frequently consume several months before physical ground-breaking even begins. Weather delays and material shipping lead times can extend the schedule further.
Does an existing home save money over a custom build in the long run?
While existing homes feature lower upfront purchase prices and avoid land acquisition costs, older properties may demand immediate capital for roof replacements, plumbing updates, or HVAC repairs that new construction entirely avoids.
How do interest-only payments work while a custom house is under construction?
Throughout the building process, you are only charged monthly interest on the exact amount of money the lender has disbursed or drawn to your contractor via completed milestone draws, rather than the total approved loan balance.
What is the most unpredictable expense when constructing a new property?
Site preparation and foundation work are universally considered the most unpredictable phases. Unforeseen subsurface conditions like poor soil bearing capacity or hidden rock formations can require sudden, expensive engineering solutions that quickly tap into contingency funds.
- Digital Agency
- Literie
- Location de voitures
- Restaurant
- Restaurant
- Mode
- Mode
- Information
- Marketing
- Tourisme
- Développement
- Découverte
- Législation
- Gastronomie
- Pâtisserie
- مناسبة
- Art
- Causes
- Crafts
- Dance
- Drinks
- Film
- Fitness
- Food
- الألعاب
- Gardening
- Health
- الرئيسية
- Literature
- Music
- Networking
- أخرى
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
 Arabic
 Indian
 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek