IV Therapy Business Insurance: 5 Gaps That Can Sink Your Clinic (and How to Close Them)
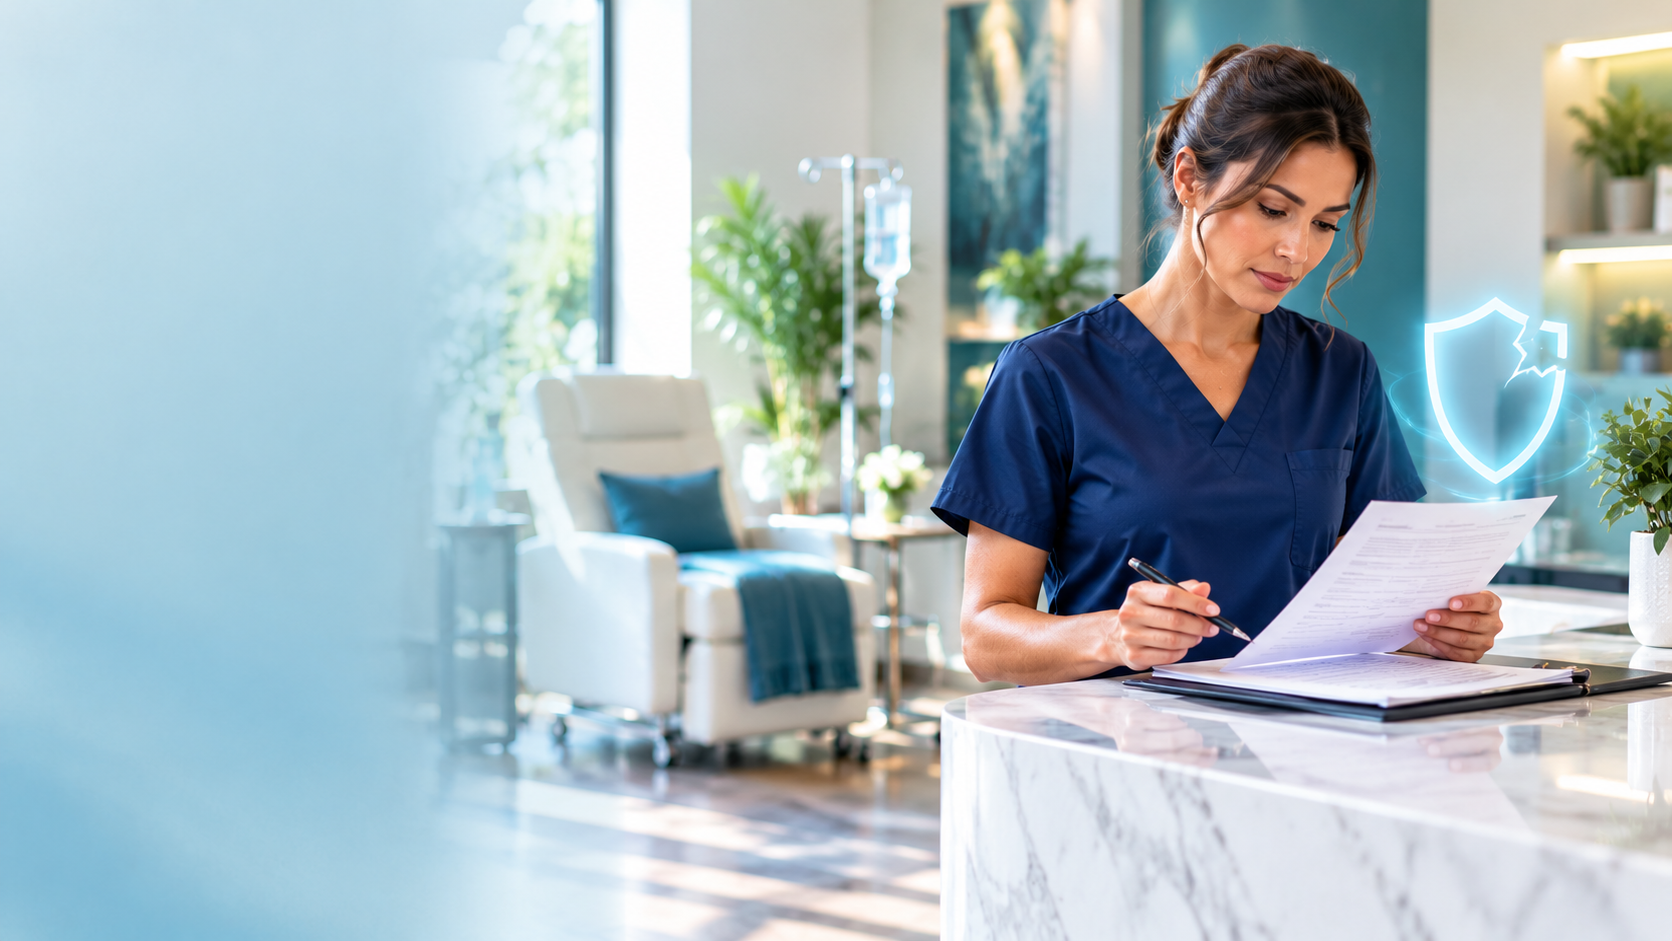
The IV hydration industry has grown fast. New clinics, mobile IV services, and med spa add-on menus are opening in nearly every market. Insurance, though, often gets handled in a rush, usually right before opening day, with whatever policy a broker can place quickly.
That's a problem, because IV therapy business insurance is not one-size-fits-all. A policy that works for a salon or a yoga studio can leave serious blind spots for a business that places IVs, handles health data, and answers to state regulators.
Below are five of the most common insurance gaps in IV businesses, why they matter, and what owners can do about each one.
Gap 1: The Policy Doesn't Name IV Therapy
Many owners assume "wellness services" or "medical spa" language covers IV infusions. It may not. Some carriers exclude infusion services, certain ingredients, or add-on injections unless they are specifically listed.
How to close it: Give your broker a complete, written service menu: every IV formulation category, injection, add-on, and delivery method (in-clinic, mobile, event-based). Then confirm in writing that those services are covered. If you add services later, notify the carrier before you launch them.
Gap 2: Relying on the Medical Director's Coverage
A supervising physician or medical director usually carries their own malpractice policy. That policy typically protects them, not your company, your nurses, or your premises.
How to close it: Ask your medical director exactly what their policy covers and whether it extends to the clinic. Then ask your own insurer how your coverage interacts with theirs. Put the roles, responsibilities, and oversight arrangements in a written agreement so that expectations are clear to everyone, including insurers and regulators.
Gap 3: No Protection Against Regulatory Complaints
Most owners picture an insurance claim as a client suing the business. But for IV clinics, a complaint to a state board or other regulator can be just as disruptive, and just as expensive to respond to. IV rules differ widely from state to state and are still evolving.
How to close it: Ask whether your policy includes regulatory or licensing-board defense, and what the limits are. If not, look into adding it. Also make it a habit to review your state's current requirements at least once a year, since a rule change can create new exposure overnight.
Gap 4: Mobile and Event Services Treated Like Brick-and-Mortar
Mobile IV is one of the fastest-growing models, but it changes the risk picture. Staff drive to client homes, hotels, and events. Supplies travel in vehicles. Care takes place in locations you don't control.
How to close it: Tell your broker how and where services are delivered. Ask about hired and non-owned auto coverage (for staff using personal vehicles), equipment and supplies in transit, and liability at off-site locations. Don't wait for a claim to find out your policy only applies to your clinic address.
Gap 5: Weak Documentation Behind the Policy
Insurance pays after something goes wrong. What insurers, attorneys, and regulators examine afterward is your paper trail: consent forms, emergency protocols, staff training records, privacy authorizations, and written policies.
If those records are missing or inconsistent, it becomes harder to demonstrate that your business followed a clear standard of care.
How to close it: Build a documentation system before you need it. At minimum, most IV businesses should have:
- Written emergency protocols that staff are trained on
- Client consent and privacy (PHI) authorization forms
- A biomedical waste plan
- A cancellation and no-show policy
- A written agreement with the medical director or collaborating provider
- An employee handbook that defines roles and expectations
These materials do double duty. They reduce day-to-day risk, and they give you something concrete to show if your coverage or compliance is ever questioned.
A Simple Annual Insurance Review for IV Clinic Owners
Set a calendar reminder to run through this list every year, and any time you add a service, hire staff, or open a new location:
- Does my service menu match exactly what my policy lists?
- Are my limits and deductibles still appropriate for my revenue and client volume?
- Do I have regulatory defense, cyber, and workers' compensation coverage where needed?
- Is my medical director arrangement documented and understood by my insurer?
- Are my forms, protocols, and training records current?
- Have my state's IV regulations changed?
Where to Find Industry-Specific Help
One of the biggest challenges for IV owners is that general insurance resources don't speak the language of the industry. That's the gap the American IV Association was created to fill.
AIVA is a national association supporting IV hydration clinics, operators, and owners with education, standards, and access to insurance designed for IV businesses, including regulatory defense coverage. Members also get state-specific regulation resources, a complimentary legal consultation through AIVA's network of legal experts, and a full library of ready-to-customize business and clinical forms.
Owners who want to go further can explore AIVA's certification standards books and its business and clinical certification programs.
Final Thoughts
Good IV therapy business insurance isn't about buying the most coverage. It's about buying the right coverage, describing your business accurately, and backing it up with clear documentation. Close these five gaps, and you'll be in a much stronger position to grow with confidence.
- Digital Agency
- Literie
- Location de voitures
- Restaurant
- Restaurant
- Mode
- Mode
- Information
- Marketing
- Tourisme
- Développement
- Découverte
- Législation
- Gastronomie
- Pâtisserie
- Evento
- Art
- Causes
- Crafts
- Dance
- Drinks
- Film
- Fitness
- Food
- Jogos
- Gardening
- Health
- Início
- Literature
- Music
- Networking
- Outro
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
 Portuguese
 Indian
 English
 French
 Arabic
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek